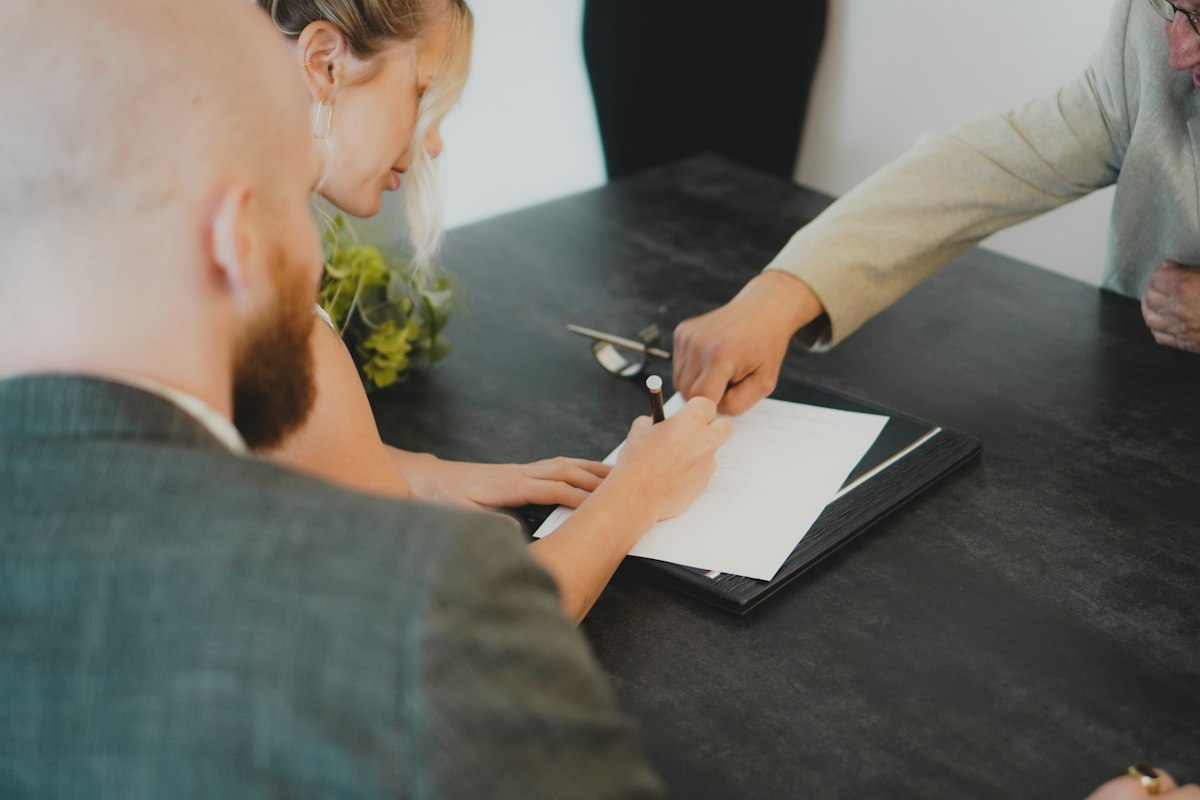
Strategic Advantages of Buying a House with Cash: A Complete Overview
Imagine walking into a real estate negotiation without the looming shadow of a mortgage underwriter. For many, buying a house with cash represents the pinnacle of financial freedom and simplicity in an otherwise complex market. It removes the stress of fluctuating interest rates, monthly debt obligations, and the risk of a deal falling through because of a bank's conservative appraisal. When you remove the lender from the equation, the transaction transforms from a bureaucratic hurdle into a direct agreement between two parties.
While most buyers rely on financing, those who can afford to pay upfront often find themselves in a position of significant power. Sellers love the certainty and speed of a cash offer, which can lead to lower purchase prices and significantly faster closing timelines. However, tying up a massive amount of liquidity into a single physical asset is a major financial move that requires careful thought. It is not just about having the money; it is about knowing how to use that capital to your advantage while protecting your long-term wealth.
Related posts
Strategies for Selling Residential Property at Top Market Value
Selling residential property is often the most significant financial transaction you will ever manage. It is a process...
Read more →
Understanding the Value of Residential Property: A Practical Guide for Homeowners and Investors
Determining the exact value of residential property is one of the most important financial steps you will take,...
Read more →Finding the Right Retreat: A Comprehensive Look at Cabins for Sale
Searching for cabins for sale often starts as a romantic endeavor. You imagine a quiet morning on a...
Read more →
Modern Living and Investment Potential in New Build Developments
Stepping into a property that has never been lived in before offers a unique sense of possibility. For...
Read more →This discussion covers the mechanics of the cash purchase, from providing proof of funds to the final closing statement. We will examine why you might choose this path, the potential downsides regarding opportunity cost, and the specific steps required to ensure the transaction is secure and legally sound. Whether you are a seasoned investor or a first-time buyer using an inheritance, understanding the nuances of a cash transaction is essential for a successful outcome.
Moving forward with a cash purchase involves more than just writing a check. It requires a strategic approach to negotiation, a clear understanding of your remaining liquidity, and a commitment to due diligence. By the end of this analysis, you will understand how to leverage your cash position to secure the best possible deal in a competitive market while avoiding the common pitfalls that can catch even the most liquid buyers off guard.
Key takeaways
- Speed and certainty are your primary leverage points when negotiating with sellers who want a fast, guaranteed exit.
- Total cost of ownership is significantly lower because you avoid decades of interest payments and various lender-related closing fees.
- Proof of funds is the most important document in the initial offer phase, replacing the traditional pre-approval letter.
- Liquidity risk must be balanced against equity, as your capital will be locked in the home and harder to access quickly.
The Leverage of a Cash Offer
In a competitive real estate market, a cash offer is often the most attractive option for a seller. But why exactly does cash carry so much weight? The answer lies in the removal of financing contingencies. Most real estate contracts are contingent on the buyer securing a loan. If the buyer’s credit score drops, their debt-to-income ratio changes, or the bank simply decides the house isn't worth the loan amount, the deal collapses. A cash buyer eliminates these variables, offering the seller a much higher probability of a successful closing.
Furthermore, cash deals can close in as little as seven to fourteen days. A traditional mortgage usually requires 30 to 45 days to process. For a seller who is relocating for work, facing financial pressure, or trying to buy another home simultaneously, this speed is a massive selling point. You can often use this speed to negotiate a lower purchase price. It is common for sellers to accept a slightly lower offer from a cash buyer over a higher offer that relies on bank financing because the cash deal is seen as a "sure thing."
Financial Benefits Beyond the Purchase Price
The most obvious financial benefit of buying a house with cash is the total absence of mortgage interest. Over a 30-year term, interest payments can nearly double the total cost of a home. By paying upfront, you are effectively "earning" whatever the current mortgage interest rate is, as you are no longer paying it to a bank. This provides an immediate boost to your monthly cash flow, as you won't have a monthly principal and interest payment to worry about.
You also save significantly on closing costs. When you take out a mortgage, the bank charges for several services, including loan origination fees, credit report fees, and mortgage insurance. You also avoid the cost of a mandatory bank appraisal, though many cash buyers still choose to get one for their own peace of mind. While you still have to pay for property taxes, title insurance, and recording fees, the overall administrative cost of the transaction is much lower.
Reduced Ongoing Stress
There is an intangible psychological benefit to owning your home outright. Without a monthly mortgage payment, your cost of living drops dramatically. This provides a safety net during economic downturns or career transitions. If you lose your job or face an unexpected medical expense, you don't have to worry about losing the roof over your head. This peace of mind is often the primary motivator for retirees or those looking to simplify their financial lives.
The Step-by-Step Process of a Cash Purchase
While the process is simpler than a financed deal, it still requires a disciplined approach. You cannot simply hand over a suitcase of money. The process begins with Proof of Funds (POF). This is typically a recent bank statement or a letter from your financial institution confirming that you have the liquid assets available to cover the full purchase price plus closing costs. You should redact your account number for security, but the seller needs to see your name and the total balance.
Once your offer is accepted, the due diligence period begins. Just because you aren't using a bank doesn't mean you should skip the home inspection. In fact, it is even more important because you are the only one protecting your investment. You want to ensure there are no structural issues, mold, or expensive roof repairs needed. If the inspection reveals problems, you can still negotiate repairs or a price reduction, or walk away from the deal if your contract includes an inspection contingency.
Title Search and Insurance
Another critical step is the title search. You must ensure the seller actually owns the property and that there are no outstanding liens, unpaid taxes, or legal disputes attached to the deed. In a financed deal, the bank requires title insurance to protect their interest. In a cash deal, you are the one at risk. You should always purchase an owner’s title insurance policy to protect yourself from any future claims against the property that weren't discovered during the search.
Understanding the Downsides and Risks
Despite the advantages, buying a house with cash is not always the right move for everyone. The biggest concern is opportunity cost. If you take $500,000 out of the stock market to buy a house, you are no longer earning potential returns on that money. If the stock market is returning 8% annually and mortgage rates are at 6%, you are technically "losing" 2% by not keeping your money in the market and taking a loan instead. You have to weigh the guaranteed "return" of avoiding interest against the potential growth of other investments.
There is also the issue of liquidity. Real estate is an illiquid asset. If you suddenly need a large amount of cash for an emergency, you cannot quickly get it out of your house. Selling a home takes months, and getting a Home Equity Line of Credit (HELOC) takes time and requires you to qualify for a loan anyway. By paying cash, you are effectively locking your wealth into the walls of the property. You must ensure you have a sufficient emergency fund remaining after the purchase.
Tax Considerations
When you pay cash, you lose the mortgage interest deduction. For many homeowners, the ability to deduct interest payments from their taxable income is a significant benefit. Without a mortgage, you lose this tax shield. While this is less of a factor than it used to be due to higher standard deductions, it is still something to discuss with a tax professional before finalizing your decision. You are essentially trading a tax break for a lower overall cost of living.
Negotiation Tactics for Cash Buyers
When you are buying with cash, you should not pay the same price as someone using a mortgage. Your offer is superior in quality, and that should be reflected in the price. How much of a discount can you expect? It varies, but many experts suggest aiming for a 3% to 5% discount compared to financed offers. You should emphasize your ability to close quickly and the fact that there is no risk of an appraisal gap where the bank refuses to lend the full amount.
Another tactic is to offer a shorter contingency period. Since you don't need to wait for a loan commitment, you can tell the seller you will have your inspection and title work done in 10 days rather than the standard 21. This demonstrates your seriousness and gives the seller peace of mind that if the deal doesn't work out, their home will be back on the market quickly rather than being tied up for a month.
Is Buying with Cash Right for You?
Deciding to buy a house with cash depends on your overall financial ecosystem. If the purchase represents 90% of your total net worth, it is likely a risky move that leaves you vulnerable to liquidity issues. However, if the purchase is a smaller portion of your portfolio, or if you are at a stage in life where eliminating debt is more important than maximizing market returns, it can be a brilliant move.
Consider your long-term goals. Are you looking for a stable place to live with minimal monthly overhead? Or are you an investor looking to flip a property quickly? The answer will dictate whether cash is the best tool for the job. Remember, you can always take out a mortgage later through delayed financing if you decide you want to pull some of your equity back out, though this comes with its own sets of costs and requirements.
Frequently Asked Questions
Do I still need an appraisal if I'm paying cash?
While an appraisal is not required by a lender when you pay cash, it is often a smart move. An appraisal provides an unbiased professional opinion of the home's value. This ensures you are not overpaying based on emotion or a lack of market data. If the appraisal comes in lower than your offer, you can use that information to negotiate a better price with the seller before closing.
How long does it take to close a cash house purchase?
A cash transaction can theoretically close in as little as a few days, but it typically takes about 10 to 14 days. The timeline is mostly dependent on how quickly the title company can perform a search and clear any issues, and how fast the buyer wants to complete their home inspection. Without the 30-day mortgage underwriting process, the timeline is much more flexible.
Is a cash offer always better than a financed offer?
From a seller's perspective, a cash offer is almost always better because it eliminates the risk of financing falling through. However, if a financed offer is significantly higher in price, a seller might choose to take the risk. For a buyer, cash is better if you value speed and interest savings, but financing might be better if you want to keep your capital invested in higher-yielding assets.
What are the tax implications of paying cash for a home?
The primary tax implication is the loss of the mortgage interest deduction on your federal income taxes. Additionally, you must ensure that the source of your cash is well-documented to comply with anti-money laundering regulations. Large cash transactions are often reported to the IRS via Form 8300 or through the title company's standard reporting procedures, so transparency is key.
How do I transfer the money safely for a cash purchase?
You should never send money directly to a seller. The funds should be handled by a neutral third party, typically an escrow agent or a title company. The most common method is a wire transfer. You must be extremely cautious of wire fraud; always verify the wiring instructions over the phone with a known contact at the title company before sending any funds. A cashier's check is another option, but many title companies prefer wires for faster clearing.
Conclusion
Buying a house with cash is a powerful financial strategy that offers unparalleled speed, simplicity, and long-term savings. By eliminating the middleman—the bank—you gain significant leverage in negotiations and remove the recurring burden of interest payments. However, this path requires a clear-eyed assessment of your liquidity and an understanding of the opportunity costs involved. It is not merely a transaction; it is a significant reallocation of your wealth into a tangible, illiquid asset.
Before you commit to a cash purchase, ensure you have conducted thorough due diligence, including inspections and title searches, and that you have a sufficient financial cushion remaining. When executed correctly, paying cash for a home can provide a level of security and financial freedom that a mortgage simply cannot match. Take the time to weigh the pros and cons against your personal financial goals to determine if this is the right move for your future.